Short-Term Rental Insurance in Ohio: What Airbnb Hosts Need Guide
Short-term rental insurance in Ohio: why your homeowners policy isn't enough
If you're renting out a room, a cabin near the lake, or your entire home on Airbnb or Vrbo, you're running a small business out of your personal property. That's good financially, but it creates a coverage gap that catches a lot of Ohio hosts off guard. Short-term rental insurance in Ohio is not the same as standard homeowners coverage, and understanding the difference before your first guest checks in could save you tens of thousands of dollars.
What standard homeowners insurance does not cover
A standard homeowners policy is written for owner-occupants, not for people renting their property to paying guests. The moment money changes hands, most carriers treat the situation differently, and many will deny a claim tied to a rental stay.
Here are the specific gaps that matter for Ohio hosts:
- Guest-caused damage: If a guest breaks furniture, stains carpet, or causes structural damage, your homeowners carrier can deny the claim because the loss occurred during a commercial activity.
- Liability for guest injuries: If a guest slips on your icy front steps or falls down a staircase, a personal homeowners liability limit (typically $100,000 to $300,000 ) may not be enough, and some carriers will contest coverage entirely.
- Theft by a guest: Personal homeowners policies exclude theft by invited occupants in many cases. A short-term rental policy treats this differently.
- Lost rental income: If a fire or covered loss makes your property uninhabitable and you lose booked reservations, a standard homeowners policy won't replace that income.
Ohio law does not require short-term rental insurance, but your mortgage lender might. If your lender finds out you're operating a short-term rental and your policy doesn't cover it, you could face a loan default scenario. Worth a conversation before you list.
How Airbnb's host protection actually works (and where it falls short)
Airbnb offers its "AirCover" protection, and Vrbo provides a similar host guarantee. These programs sound reassuring, but they are not insurance policies. They are contractual protections offered by the platform, and there are real limits to what they cover.
The key limitations Ohio hosts should understand:
- Airbnb AirCover covers up to $3 million in liability and up to $3 million in property damage from guests, but it excludes a long list of scenarios including cash, securities, vehicles, and losses tied to natural events.
- Platform protection is secondary: AirCover and similar programs typically require you to first exhaust your own insurance coverage. If you have no policy, the claim process becomes much more complicated.
- Disputes take time: Platform guarantee claims go through the company's internal process, not an independent insurance adjuster. Hosts regularly report weeks or months of back-and-forth before resolution.
- Vrbo's program has a lower property damage cap and requires hosts to purchase their own liability coverage to unlock the full benefit.
Platform protections are a supplement, not a substitute. Ohio hosts who rely on them exclusively are exposed.
Types of short-term rental insurance available in Ohio
The market for short-term rental coverage has grown significantly. Ohio hosts have several real options depending on how often they rent and what kind of property they have.
Homeowners policy with a short-term rental endorsement
Some carriers will add a short-term rental endorsement to your existing homeowners policy. This is the simplest path if your carrier offers it, and it closes the gap for occasional rentals (typically under 90 days per year). Not every Ohio carrier offers this, and the endorsement may cap the number of rental nights covered.
Standalone short-term rental insurance
Companies like Proper Insurance, Slice, and a handful of others offer policies written specifically for short-term rental hosts. These policies are designed around the risks that come with rotating guests: higher liability limits, guest-caused damage, bed bug coverage, and loss of rental income. Premiums for a $300,000 home in Ohio typically run $1,500 to $3,500 per year depending on how frequently you rent and the location.
Commercial landlord or dwelling fire policy
If you own a property you rent out full-time as a short-term rental (meaning you don't live there), a landlord insurance or dwelling fire policy is often the right starting point. These are structured for non-owner-occupied rentals and can be endorsed for short-term rental activity. They typically cover the structure, liability, and lost rental income.
Personal umbrella policy
Regardless of which base policy you choose, a personal umbrella policy adds an extra layer of liability protection above your primary coverage limits. For hosts renting in high-traffic areas or properties with pools, hot tubs, or fire pits, a $1 million umbrella can be purchased for roughly $150 to $300 per year and is well worth the cost.
Ohio-specific risks that short-term rental hosts should think about
Ohio's geography and climate create a specific risk profile for short-term rental properties. Whether you're hosting near Lake Erie, in a rural cabin in the Hocking Hills area, or in a city property in Cleveland or Columbus, the exposures below are worth building coverage around.
Winter weather and ice
Ohio winters are serious. Ice dams, frozen pipes, and icy walkways are real liability hazards for short-term rental hosts. If a guest slips on an icy step you hadn't cleared, a standard homeowners policy may not cover the resulting injury claim. Your short-term rental policy should include premises liability that applies when guests are on site.
Lake Erie proximity and flooding
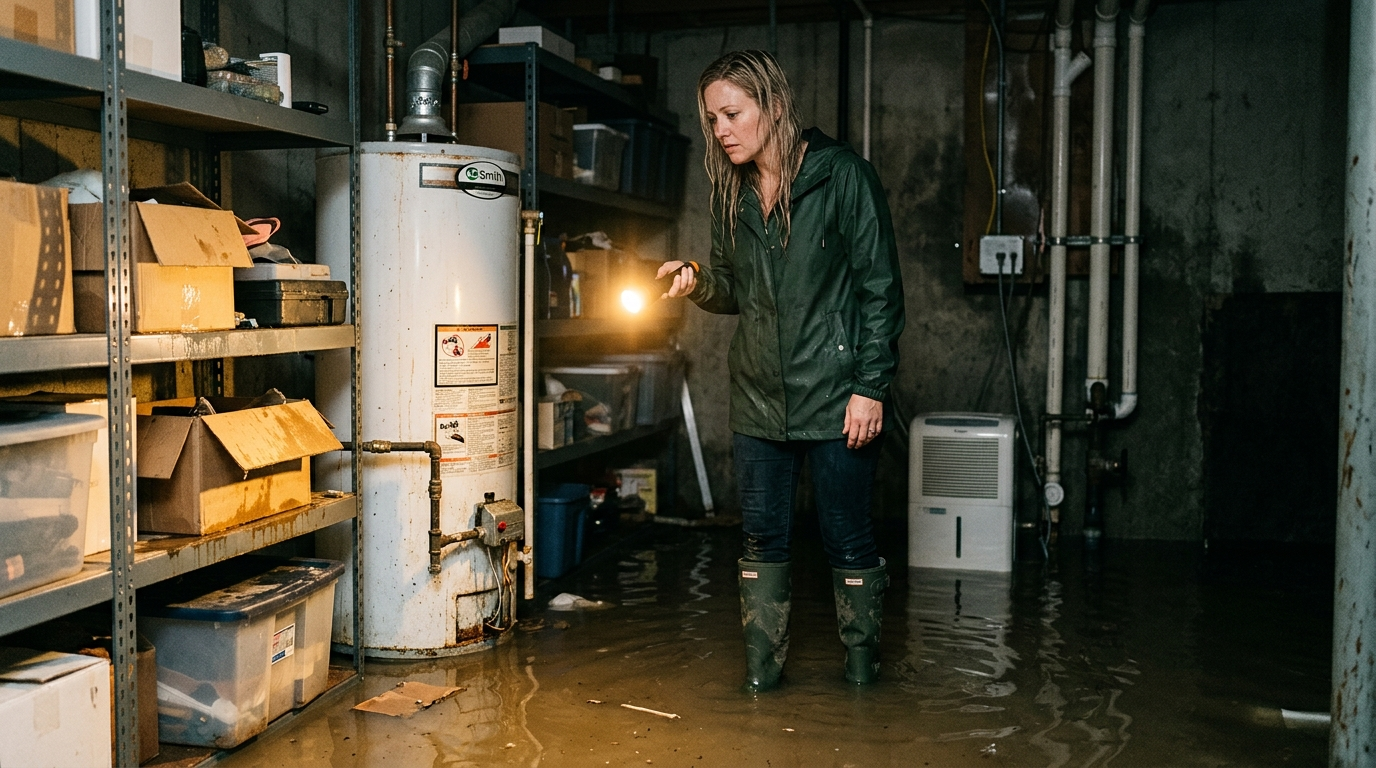
Properties near Lake Erie or in the Cuyahoga, Grand, or Chagrin River floodplains carry flood risk that is excluded from virtually every standard property policy. If your short-term rental property is in a flood zone or near these waterways, a separate flood policy through the National Flood Insurance Program (NFIP) or a private carrier is not optional. Flood damage to a rental property with no flood coverage means you absorb the full repair cost yourself.
Guest pools, fire pits, and recreational amenities
These are major selling points for short-term rentals, and they are also major liability exposures. A pool increases your liability risk significantly. Make sure your policy specifically covers pool-related incidents and that your liability limits are high enough to cover a serious injury claim.
Seasonal or vacant periods
If your rental property sits empty between bookings for stretches of time, some standard policies apply a vacancy clause after 30 to 60 days that reduces or eliminates coverage. A short-term rental policy should handle intermittent occupancy without penalizing you during off-season gaps.
What short-term rental insurance typically costs in Ohio
Cost varies based on the value of the structure, your location, how many nights per year you rent, the amenities you offer, and the coverage limits you choose. Here are realistic ranges Ohio hosts can expect:
- Endorsement on existing homeowners policy: Often $200 to $500 per year added to your existing premium for occasional rentals.
- Standalone short-term rental policy: Typically $1,500 to $3,500 per year for a property valued at $200,000 to $400,000 , renting frequently.
- Landlord policy with short-term rental activity: Ranges from $800 to $2,500 per year depending on the structure and location.
- Umbrella add-on: An additional $150 to $300 per year for $1 million in excess liability protection.
Hosts who shop based on price alone often end up with coverage that excludes the exact scenarios most likely to generate a claim. Working with an independent agent who can compare multiple carriers side-by-side gives you a much clearer picture of what you're actually buying.
Questions to ask before you choose a policy
When you sit down with an agent (or review a policy on your own), these are the questions that will separate a solid short-term rental policy from one that leaves gaps:
- Does the policy cover guest-caused damage , not just accidental damage from external events, but damage a guest intentionally or carelessly causes?
- What is the liability limit, and does it apply specifically when paying guests are on the premises?
- Is lost rental income covered, and what triggers the benefit? Does it require a covered property loss, or does it extend to government-ordered closures?
- How does the policy handle intermittent occupancy? Will coverage hold during a two-week gap between bookings?
- Are recreational amenities like pools or hot tubs specifically covered, or excluded?
- Does the policy coordinate with or exclude platform protections like Airbnb AirCover?
If an agent can't answer these questions clearly, that's a sign to keep shopping.
Get the right coverage for your Ohio rental property
Short-term rentals are a real and growing part of Ohio's housing economy, and the insurance market has caught up with the demand. But policies are not all equal, and the differences between a solid policy and a thin one often only become clear at claim time.
At Love Insurance Agency , we are an independent agency, which means we work with multiple carriers to find coverage that actually fits your situation. Whether you rent your home a few weekends a year or operate a dedicated vacation property full-time, we can compare options across the market and help you understand what you're buying before you need to use it.
If you're already renting short-term without the right coverage in place, the time to fix that is now, before a claim happens. If you're just getting started, we can make sure you're protected from day one. You can also explore our short-term rental insurance options or read our related guide on landlord insurance in Ohio if you own multiple rental properties.
Reach out to Love Insurance Agency at (440) 527-5050 or contact us online to get a quote and talk through your specific property. We're here to make sure your guests have a great stay and you have real protection if something goes wrong.
Get A Quote
At Love Insurance Agency, securing your future is easy. Ready to protect what matters? Contact us for a quick quote and personalized insurance options!
Kelly
Speak to Kelly 24/7
Microphone ready
Start your custom insurance quote
Instant answers to your insurance questions
Schedule appointments or follow-ups
Personal Insurance
From auto and homeowners to renters and umbrella policies, we help protect your family and property. Let’s find coverage that fits your life.
Commercial Insurance
We customize policies for your industry's risks, like general liability and workers' comp, ensuring you can run your business worry-free.
Contact Love Insurance Agency
info@segurosidealinc.com
373 Center Street, STE A, Chardon, Ohio 44024, United States